|
|
What 1,339 valuations tell us about the private market |
|
Every valuation we complete at bizval tells us something about the business behind it.
Over the past year, we have conducted 1,339 private company valuations globally. In unpacking these, a clearer picture starts to emerge: not just of what businesses are worth, but of the owners behind them, their intentions and the decisions behind the numbers, whether they are considering a sale, planning ahead or simply curious.
We thought we’d unpack some of our internal data to see if there were any nuggets worth exploring. So, here’s what the past 12 months’ data shows: |
The headline numbers
|
We completed 1,339 valuations in the 12 months to 30 June 2026, up from 1,085 the year before. Over $7 billion in combined business value was assessed. The average valuation was $5.1m, with the largest valuation at $330m. We operate squarely in the global mid-market space, with the average influenced by regional differences. By region, the US accounts for 35.8% of businesses valued and the UK for 26.2%, with the balance coming largely from the EMEA region at 29% and the rest of the world, including Australia, at 9%. In terms of value, just under 50% of valuations are for defensible purposes, which we’ll break down a little further later, while the balance is largely for advisory or strategic planning purposes. Not every valuation needs to be fully defensible in the traditional sense, and that is where our quicker and more affordable advisory tier comes in. What is interesting, however, is that the underlying value of businesses requiring defensible valuations tends to be three to four times higher than that of businesses requiring advisory valuations. |
What you ask for tells us where you actually are
|
 |
It would be easy to assume that the split between defensible and advisory valuations reflects budget. It doesn’t. It reflects stakes. Advisory valuations are mostly exploratory. Of these, 36% were commissioned because of a potential sale, and 35.5%, almost the same number, were driven by pure curiosity: an owner wanting to know where they stand, with no transaction in motion. Strategic planning accounted for another 10%. Two-thirds of advisory clients, in other words, are still forming a question rather than answering one. These are usually situations where knowing the valuation is important but not necessarily urgent. Defensible valuations tell a different story. Of these, 43% were commissioned for exits already underway, 34% for formal planning, and the remaining 23% were split between disputes and fundraising. These are situations where the number has to survive scrutiny from a counterparty, court or investor, rather than simply satisfying the person who requested it. There is also usually an increased level of urgency in these instances, with a deal deadline, arbitration date or board meeting looming. Put together, advisory valuations are where the market is thinking. Defensible valuations are where it has already decided. For accountants and advisors, that makes the advisory tier itself diagnostic. A client asking “just to see” is often a year or two away from a real decision, while a client who needs a defensible valuation usually already has a specific decision in front of them. For wealth managers, lawyers and dealmakers, curiosity-driven engagements are worth watching rather than dismissing. They are frequently the first documented step in a process that becomes formal months later. |
Sector matters more than owners think
|
 |
The type of valuation, whether advisory or defensible, isn’t the only thing that moves the number. Sector does too, and often by more than most owners expect. Across this year’s full valuations, the median EBITDA multiple ranged from 3.0x in physical retail and media to 5.4x in education. Financial services at 4.8x, e-commerce at 4.7x and software at 4.5x all reached or exceeded 4.5x, while manufacturing and restaurants sat closer to 3.3x. This was barely above physical retail, despite their very different operating models. This is a global reference point, with further differences between regions and countries becoming evident when one looks even deeper. The practical effect is that the same $500,000 of EBITDA is worth roughly $1.5m in one sector and $2.7m in another. None of that gap shows up on a P&L. It comes from how repeatable the earnings appear, how dependent they are on the owner personally, and how actively that sector is currently being bought and sold. An owner or advisor benchmarking against “the market” without adjusting for sector is often anchoring to the wrong number before the conversation even begins.
|
What separates a 2.9x business from a 5.7x business?
|
Sector sets the range. Within that range, something else is doing the work. The median EBITDA multiple applied across our full valuations over the past 12 months was 3.8x, up from 3.5x the year before. But the median hides more than it shows: the middle half of the businesses we valued fell anywhere between 2.9x and 5.7x. Two businesses generating the same profit can be valued at nearly double one another, and sector alone doesn’t explain it. What usually does explain it is how much of that profit depends on the owner remaining involved, how concentrated the customer base is, how clean and current the financials are, and how much of the revenue is contracted or recurring rather than won afresh each year. None of these factors appears as a single line item, but together they are often the difference between the bottom and the top of the range. One further shift worth noting is that the discount rates applied in our valuations eased by 2% over the year, providing a modest tailwind as the perceived risk in these businesses declined. Combined with the increase in multiples, it is reasonable to conclude that buyers and valuers alike are pricing slightly more confidence into private business earnings than they were during the previous 12 months. Median trailing price-to-earnings across these engagements sat at 7.8, providing context alongside the EBITDA figures. That said, current geopolitical developments had only a limited effect over the measurement period. For accountants and advisors preparing a client for sale, the 2.9x–5.7x spread is a useful conversation starter. It reframes “What’s my business worth?” as “What would move me towards the top of that range?”, which is a more productive and usually more actionable question.
|
Before you trust a number
|
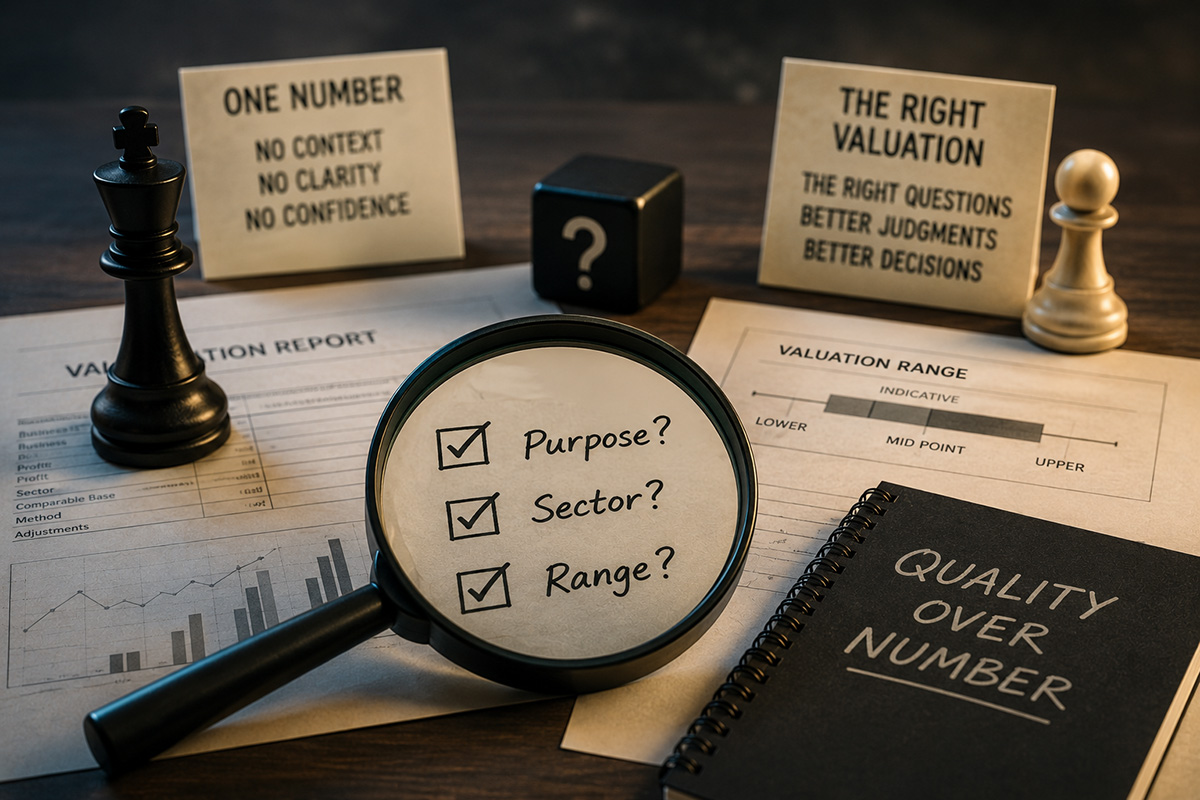 |
Put this year's data together and a practical checklist emerges, one worth applying to any valuation you're given, ours or otherwise. What was it for? A number produced out of curiosity and a number produced to survive a dispute or a lender's scrutiny are built to different standards, even if the business is identical. Know which one you're holding before you rely on it. Does it account for sector? A multiple pulled from "the market" in general is close to meaningless. The same profit is worth nearly double depending on sector alone. Ask what the comparable base actually was. Where does it sit in the range? If a valuation gives you a single figure with no sense of where that sits relative to the sector's spread, you're missing the more useful half of the analysis. The range tells you what would move the number, which is usually what you actually came for.
None of these questions requires a finance background. They simply require an understanding that “What’s my business worth?” is rarely a one-number question. It involves a set of judgements, and the quality of a valuation is reflected in how well those judgements are made, not in the number itself. If you are interested in understanding the more detailed insights underpinning these high-level numbers, reach out to us at value.me@bizvalglobal.com |
Recent podcasts
|
|
|
 |
27 years of building an independent investment bank in Southern Africa
In this episode, Graham speaks with Soria Hay, co-founder and Head of Corporate Finance at Bravura, one of Southern Africa's leading independent investment banking firms. Soria and Graham trace the path from a childhood moving frequently as a minister's daughter, through five years of funding her own law degree on shop floors and bank tills, to the realisation that law was too reactive for where she wanted to be. They also get into the deals that shaped her: a ten-year journey with a renewable energy founder that ended in a R1.8 billion transaction, a billion-rand merger that collapsed at due diligence and led to insider trading findings and testimony at the FSB, and a recent decision to walk away from a mandated deal because the buyer's values didn't sit right for the client. Listen here.
|
When entrepreneurship meets law
In this episode, Graham speaks with Steven Landsberg, a corporate commercial attorney, founder of Landsberg and Co, and co-founder of Briefcase, a legal tech and education platform. Steven and Graham trace the path from his first venture, built out of an almost panicked need to own something, through Briefcase's pivot from legal operating system to an AI-guarded education platform They also talk candidly about billing: why Steven moved away from the hourly model entirely, what that shift actually costs a practice in the short term, and why he thinks it was never really in the client's interest to begin with. Listen here.
|
AI, valuation, and the future of the profession
In this episode, Graham speaks with Rod Burkert, who has spent nearly four decades moving through tax accounting, Fortune 500 manufacturing, and Wall Street before spending 20 years running his own valuation practice. Today he coaches valuation professionals through rbCOACHING and writes AI for BV, the only newsletter focused specifically on artificial intelligence for the valuation, forensic, and litigation services profession. Rod and Graham talk through what actually built his practice: a level of specialisation most solo practitioners never commit to, before turning to the question every valuer is quietly asking. AI isn't the threat. A peer who's figured out how to use it well is. This is a conversation about staying essential in a profession that's about to split sharply between those who adapt and those who don't, and where Rod thinks that line will actually fall. Listen here. |
|
|
Putting ourselves in the buyer’s position
|
 |
Our CEO Graham Stephen was recently in London and attended another fantastic meeting of The Executives’ Association of Great Britain. This particular meeting brought together a wide range of like-minded individuals to discuss the value of stepping into a buyer's mindset, where the real opportunities lie in investing in people, and how to stay present-minded.
It was good company and good conversation on both fronts and a valuable investment of time into the UK bizval community. |
Until next time, The bizval team |
|
|
|
|
|


