|
|
The valuation that survives cross-examination |
|
Here's an uncomfortable truth for anyone relying on a valuation in a dispute, a transaction, or a tax filing: being right isn't enough. Whoever is testing your number could be a judge, an opposing expert, or a tax inspector. None of them are asking whether the figure is correct. They're asking whether the reasoning that got you there is transparent, consistent and built on something more solid than professional confidence. In the US, that standard has a name: Daubert v. Merrell Dow Pharmaceuticals, decided in 1993 and extended explicitly to financial and other non-scientific experts six years later in Kumho Tire Co. v. Carmichael. Together, these rulings turned judges into gatekeepers. Before a jury ever hears an expert's opinion, the judge decides whether the reasoning behind it is reliable enough to be heard at all. Get excluded at that stage, and it doesn't matter how sound your underlying number was. It never reaches the people deciding the case. But the discipline behind Daubert isn't an American peculiarity. It just happens to be the most litigated, most publicly documented version of a test that shows up almost everywhere a valuation gets used in earnest. UK courts apply the same underlying expectation under Part 35 of the Civil Procedure Rules. And for a huge amount of UK valuation work, the test never goes near a courtroom at all. Instead, it shows up as a query letter from HMRC's Shares and Assets Valuation team. Different names, different institutions, same underlying question: show your working, or don't expect to be believed. The numbers back up how real this risk is. A 2025 analysis of Daubert challenges brought against economists in antitrust litigation found that opinions were fully or partially excluded in 36% of 286 challenges over the study period. That's more than a third gone before a jury ever heard them. It's a coin flip with bad odds, applied to opinions prepared by qualified, credentialed professionals. |
 |
Five ways a valuation actually gets challenged
|
Strip away the legal language and the recurring grounds for exclusion come down to the same five practical failure points, regardless of jurisdiction or industry. |
Unsupported methodology. Choosing a widely accepted approach isn't enough on its own; the choice has to fit the facts of the case. A discounted cash flow analysis is about as textbook as valuation methodology gets, but courts have shown that they'll dig into why that particular method was selected for this particular business, not just whether it's theoretically sound in the abstract. An accepted methodology poorly applied is still a target. Conclusions without a visible path. Experience is not an analysis. If a valuation's material assumptions, such as growth rates, discount rates, capitalisation rates, or the selection of comparable companies, can't be traced back to identifiable evidence in the record, you're in trouble. "Trust me, I've done this for twenty years" won't hold up under cross-examination. Courts have a name for this: ipse dixit reasoning, essentially "because I say so." It's one of the most consistently punished failure modes in expert testimony, precisely because it's the easiest one to fall into when an expert is confident in their own judgement. Inconsistent application. This is the one that catches people out, often unintentionally. Changing an assumption partway through an analysis without explanation, or including some comparable companies while quietly excluding others that don't help the conclusion, invites exactly the kind of scrutiny that unravels an otherwise defensible opinion. It doesn't have to be deliberate to be damaging. A change made for good reason, but left unexplained on paper, looks the same to opposing counsel as one made for a bad one. Independence in question. Prior audit work, prior advisory relationships with a party, or compensation structures tied to outcome don't automatically disqualify an expert. But they hand opposing counsel a ready-made line of attack, and in a dispute where every other element of the analysis is solid, independence is often where cross-examination goes to work first. Process discipline. In US federal litigation, Rule 26 of the Federal Rules of Civil Procedure sets out exactly what an expert report has to disclose: the opinions offered, the facts and data considered, exhibits relied on, qualifications, prior testimony, and how the expert is being paid. Courts have shown very little patience for reports that are incomplete or filed late, particularly where the gaps make it harder for the other side to prepare a proper cross-examination. A brilliant analysis, badly disclosed, can create problems that have nothing to do with the substance of the opinion at all. |
None of these five is fatal on its own. But together, they explain why so many valuations that are numerically sound still don't survive the room they're tested in. |
A case in point
|
 |
In 2014, the First Circuit heard an appeal in Bricklayers & Trowel Trades International Pension Fund v. Credit Suisse Securities, a case stemming from the 2001 AOL–Time Warner merger, where shareholders alleged that misstatements from Credit Suisse First Boston had artificially inflated AOL's stock price. The plaintiffs' expert built an event study around 57 dates where he argued the market had reacted to the alleged misstatements. The problem: several of those dates involved information that was already public, not genuinely new to the market and the study didn't account for other factors that could just as easily explain the price movements. The court excluded the study. Notably, even though roughly five of the 57 event dates arguably held up under scrutiny, the First Circuit found the trial court was within its rights to throw out the entire analysis rather than salvage the surviving fragments. Without that expert testimony, the plaintiffs had no way to establish that the alleged misstatements had actually caused their losses. A decade-long case ended, not because the underlying claim was hopeless, but because the analysis meant to prove it didn't hold together. It's all about building trust and credibility. Selective inclusion of data, however defensible each individual choice might seem in isolation, can be enough to sink an otherwise credible analysis. Courts have consistently shown they'd rather exclude an entire opinion than try to separate the reliable parts from the unreliable ones. |
It's not just judges who ask the question
|
 |
For UK practitioners, the more familiar version of this scrutiny probably doesn't come from a courtroom at all. HMRC's Shares and Assets Valuation team reviews valuations of unquoted shares across a wide range of everyday tax work, including EMI option grants, employment-related securities returns, post-transaction valuation rulings and share-for-share exchanges. SAV has become noticeably more exacting in recent years about the same things a Daubert challenge would target. The pattern of pushback is familiar: methodology asserted rather than justified, with a multiple applied but no comparable peer set or sense-check behind it; discounts for marketability or minority interest pulled from convention rather than built up from evidence; a recent funding round or share transaction quietly ignored or discounted away without explanation; financials that are stale rather than current. SAV doesn't just want a number. It wants to see the chain of reasoning from evidence to conclusion, with every link able to stand on its own. The consequence of getting it wrong isn't a courtroom exclusion, but it isn't trivial either. A poorly evidenced EMI valuation that HMRC won't agree can mean the option loses its intended tax treatment entirely, an outcome that lands on the employee, not just the company. Different forum, different stakes, same underlying lesson: a valuation that can't show its working doesn't get the benefit of the doubt.
|
 |
Before it gets anywhere near a courtroom, or a tax inspector
|
The best defence against all of this is built long before anyone asks to see it, in the file itself:
|
Document why a method was chosen, not just that it's an accepted one. Trace every material assumption back to identifiable evidence, not professional judgement alone. Apply the same standard consistently across comparable issues within the same opinion. Disclose relationships and compensation structures upfront, rather than leaving them for opposing counsel, or a reviewer, to surface. Keep the working file as complete as the report itself. A conclusion without a visible trail back to the evidence is a conclusion waiting to be challenged.
|
None of this guarantees admissibility, or agreement, or approval. But a valuation built this way gives itself the best possible chance of being heard on its merits. That's true whether the audience is a jury, a judge, or a caseworker at HMRC and it's often the whole battle.
|
 |
When the split needs to stand up to scrutiny
|
A recent bizval instruction put that discipline to work ahead of a capital raise. A group needed an independent basis for allocating a bridging rights issue between two operating companies in different jurisdictions. One was already profitable. The other was building its international footprint, with parts still pre-revenue. Existing and incoming shareholders held different interests in each, so the reasoning behind the split mattered.
We valued each company separately, with assumptions that reflected its own risks and growth prospects. The expansion forecast was tested against signed pipeline contracts and the board-approved plan and comparable transactions provided a cross-check. Every material assumption had a documented source.
Within two weeks, the board had an independent basis for the allocation, including sensitivity analysis showing how the split would move if key assumptions changed. A practical example of what it means to show your working when different shareholders have different stakes in the answer.
Read the full case study.
|
Recent podcasts
|
|
|
 |
Leadership lessons from a life built on Ubuntu
In this episode, Graham speaks with Kevin Chaplin, founder of the SA Ubuntu Foundation, Managing Director of the Amy Foundation, and author of Can Do! Making the Impossible Possible! After 26 years in banking, Kevin made the shift to community leadership and his perspective on resilience and purpose comes from having tested it in both worlds. Graham and Kevin discuss what servant leadership actually looks like in practice, why Ubuntu functions as a working leadership framework rather than an abstract philosophy and how the discipline built over a banking career translates into building organisations that last. Listen here.
|
In case you missed it
|
27 years of building an independent investment bank in Southern Africa
In this episode, Graham speaks with Soria Hay, co-founder and Head of Corporate Finance at Bravura, one of Southern Africa's leading independent investment banking firms. Soria and Graham trace the path from a childhood moving frequently as a minister's daughter, through five years of funding her own law degree on shop floors and bank tills, to the realisation that law was too reactive for where she wanted to be. They also get into the deals that shaped her: a ten-year journey with a renewable energy founder that ended in a R1.8 billion transaction, a billion-rand merger that collapsed at due diligence and led to insider trading findings and testimony at the FSB and a recent decision to walk away from a mandated deal because the buyer's values didn't sit right for the client. Listen here.
|
Why most exits fail before they even start
|
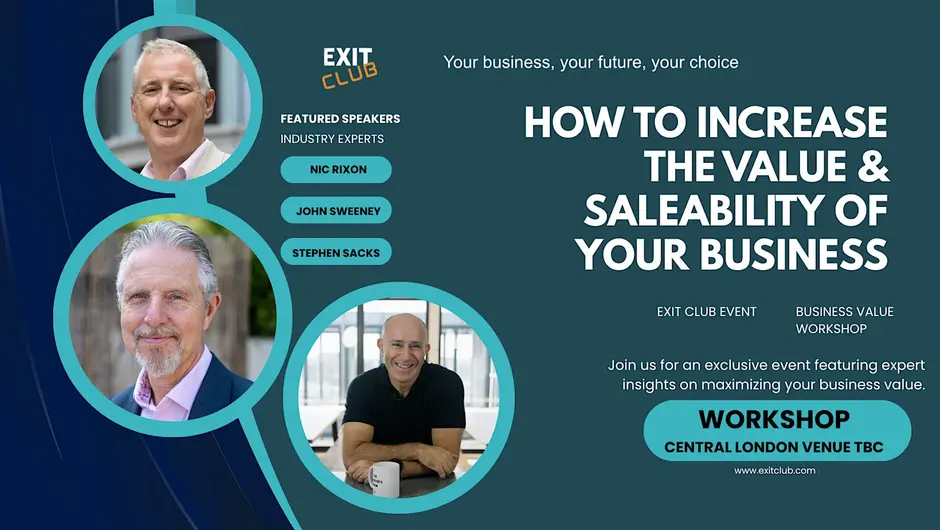 |
Roughly 80% of businesses that go to market never actually sell. Not because they're bad businesses, but because they were never built to run without the owner. That’s why we’re excited to share this in-person workshop, hosted by the Exit Club team, for founders and CEOs thinking about an eventual exit, whether that's 18 months out or five years away. John, Nic, and Stephen have built, sold and exited multiple businesses over the past 25 years, and they'll cover what actually drives buyer interest: owner dependence, revenue quality, and the practical steps that separate a business that sells from one that doesn't. If exit is on your radar at all, this is worth two hours. Thursday, October 8, 10am–12pm | Central London Reserve your spot here. |
Until next time, The bizval team |
|
|
|
|
|